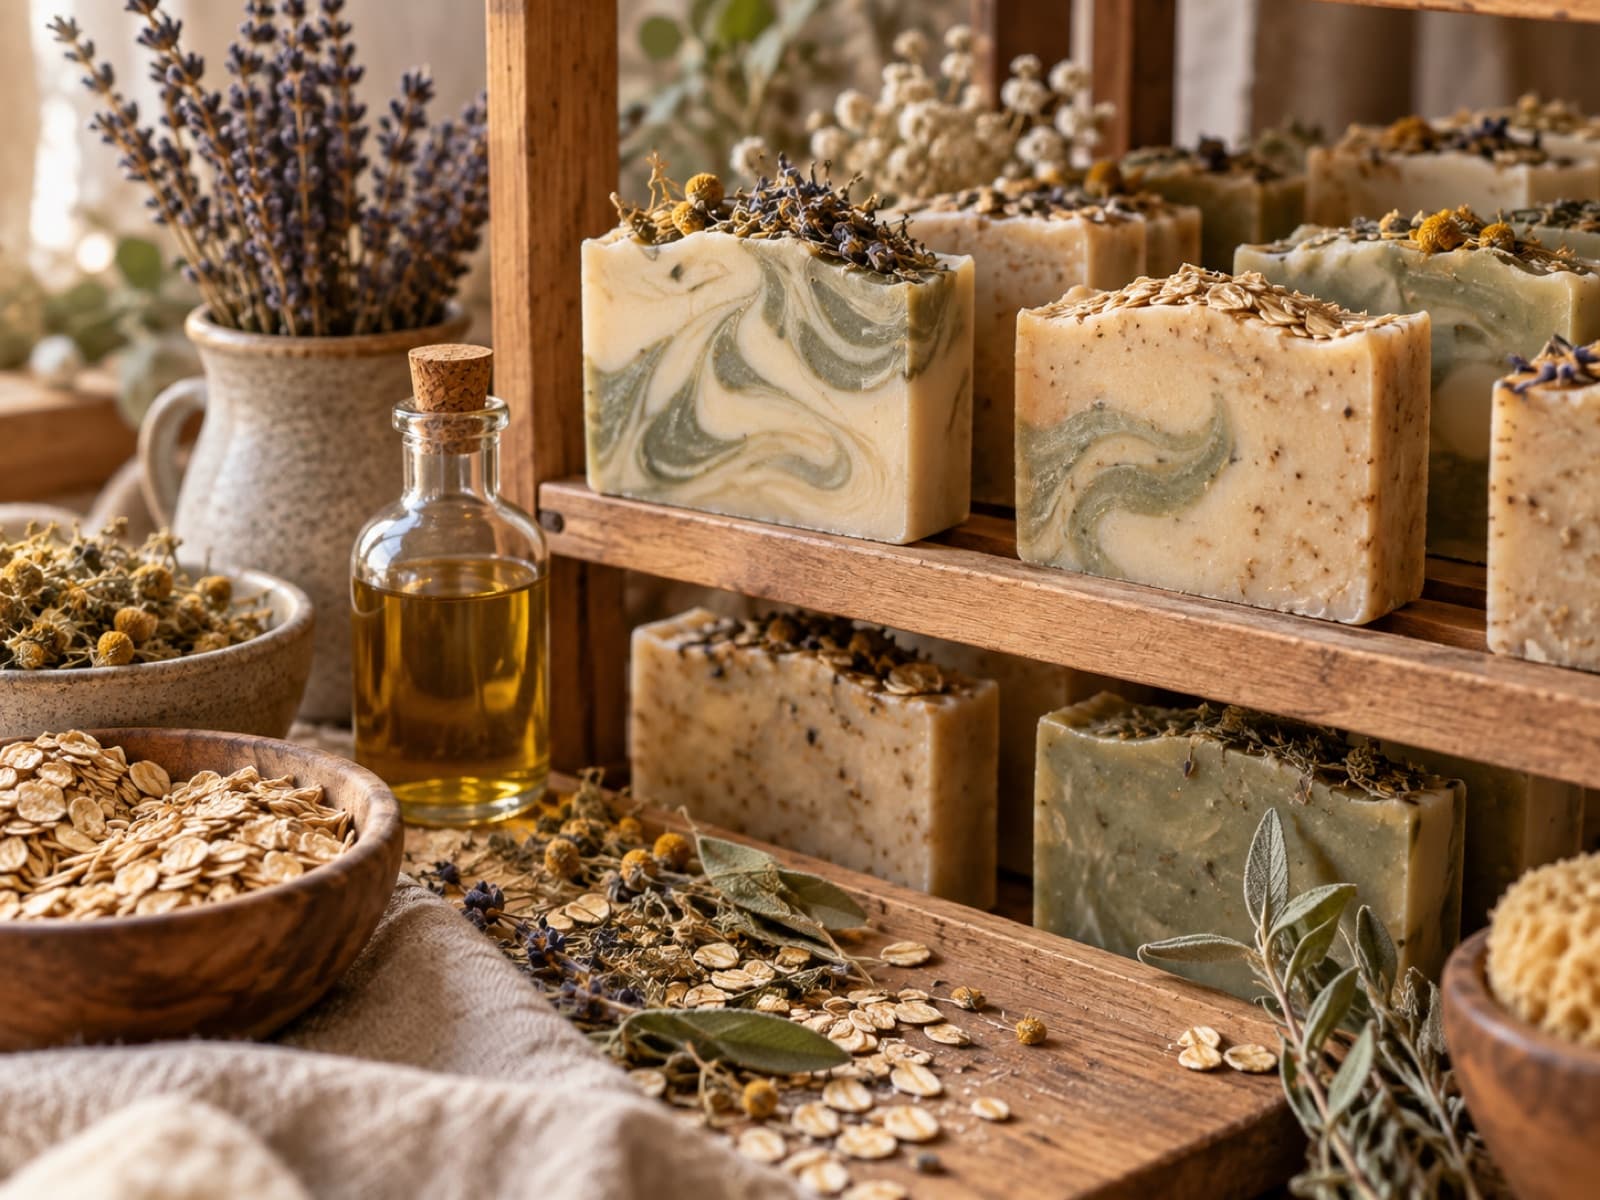
The number cut is not always the number sold.
You cut the loaf, tidy the edges and set a few pieces aside. The bars you can actually sell need to carry the batch’s cost, including the ingredients that never make it into a full-size bar.
Put it in your calculation
Record the batch yield you can sell. Account for losses through that yield or a separate allowance, without charging for the same loss twice.